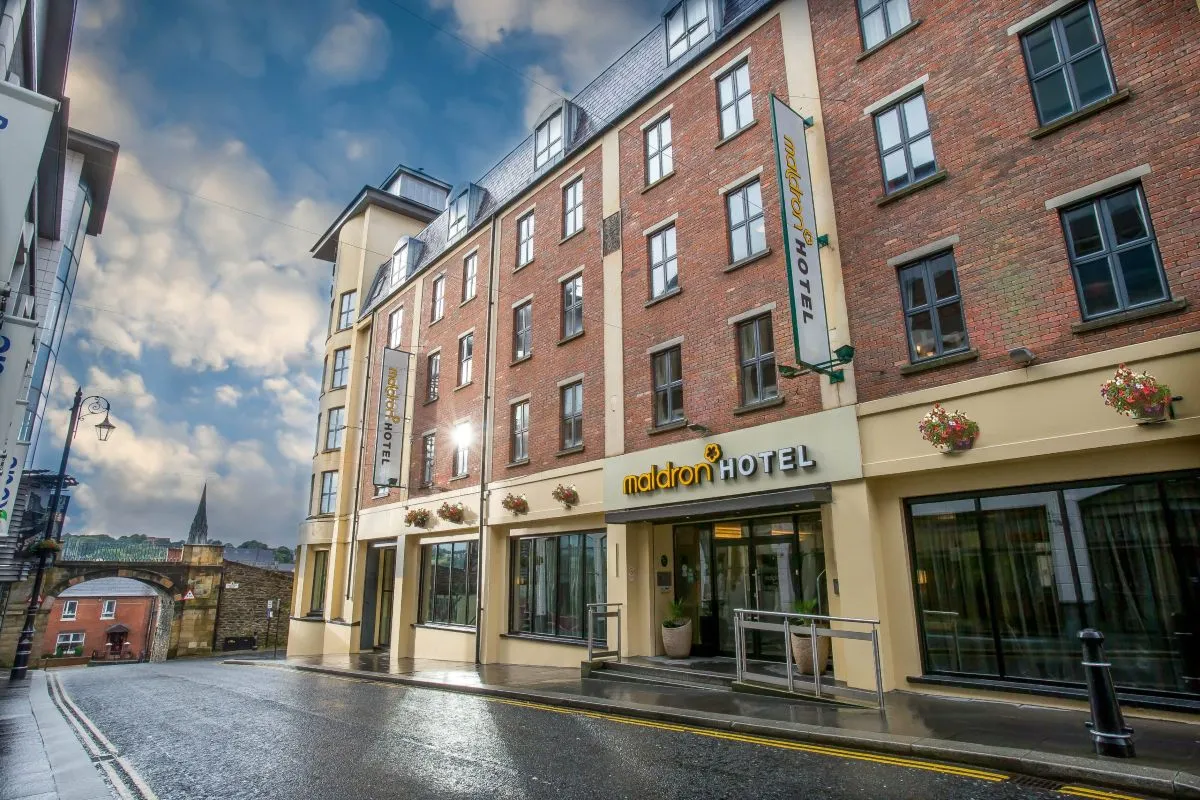
Scandic Hotels Group's €500 million acquisition of Dalata Hotel Group delivered results that justified the purchase price. Third-quarter figures released Tuesday, the first report since the deal closed eight days prior, showed a 24% lift to pro forma earnings per share.
The gap in occupancy rates explains the deal's value. Dalata's 57 hotels in Ireland and the UK fill 80% of their rooms, compared to 65% occupancy at Scandic properties. Scandic had operated Dalata's hotels under a management agreement for a year before completing the acquisition.
On a pro forma basis treating the companies as combined for the full 12 months to September 30, the group generated SEK 30.4 billion (about $3.05 billion) in revenue and SEK 3.35 billion (about $336 million) in adjusted EBITDA, an 11% margin. Pro forma earnings per share, adjusted for new financing costs, reached SEK 6.65 (about $0.67), against SEK 5.35 (about $0.54) for Scandic standalone.
The challenge ahead centers on integration. Scandic must move carefully enough to preserve Dalata's higher occupancy rates that made the acquisition attractive in the first place.